Gold is not an unconditional safe haven. It is a regime-dependent insurance asset that works in some shocks and fails in others, a conclusion backed by the International Monetary Fund and the Bank for International Settlements. Bitcoin can hedge in select episodes, but its volatility and dependence on market liquidity make it a less consistent alternative than gold's long documented track record.
TL;DR:
- Gold's hedge effectiveness varies significantly depending on the type of market shock, performing better during financial or liquidity crises than commodity or political risks.
- Reserve manager data indicates that gold reserve value increased mainly due to price appreciation, with physical holdings remaining stable in advanced economies in 2025.
- Bitcoin reacts faster and more volatile to market fear, but it lacks the long-term stability and dual use of gold, making it less reliable as a hedge.
- A modest gold allocation of 0 to 5% aligns with typical portfolio strategies, with higher stakes justified mainly by high duration or tail risks, not by chasing record prices.
Table of Contents
- What the evidence says: IMF, BIS, and academic research
- How gold compares with Bitcoin and crypto in stress episodes
- Why gold's safe-haven role is regime dependent
- Implications for portfolio sizing and practical rules of thumb
- Publisher perspective: trading gold vs owning it
- Author's quick take for investors today
- An alternative for active gold exposure worth a closer look
- Sources
- FAQ
What the evidence says: IMF, BIS, and academic research
The central-bank data reframes the popular gold story. Official reserves surged in market value during 2025, but the IMF found this was largely a valuation event rather than a buying spree: physical gold stocks stayed roughly flat in advanced economies, while emerging-market holdings grew by a modest amount. Reserve managers are not necessarily accumulating more metal. They are watching the metal they already hold appreciate.
Three findings stand out:
- The market value of official gold reserves rose 58.8% in 2025 to about 3.7 trillion SDR, according to the IMF, a jump driven by price, not physical accumulation.
- The BIS finds that stablecoins and crypto assets decline after monetary policy shocks and do not reliably behave as safe havens during traditional market stress.
- Academic work summarized on Duke's research page, including studies by Erb and Harvey and by van Vliet and Lohre, finds gold's protective effect depends heavily on the type of shock and the time horizon involved.
The IMF's July 2026 note found gold's hedging benefits are regime-dependent, performing better against financial or liquidity shocks than against commodity-driven or election-related risk. That single distinction explains why gold sometimes rallies hard during a crisis and sometimes just sits there.
The academic literature adds a caution: equities and gold fell together in about 17% of months studied, and gold only served as a reliable haven in roughly 75% of down markets for equities when measured over a three-year horizon. Short-term protection is far less dependable than the three-year figure suggests.

How gold compares with Bitcoin and crypto in stress episodes
Gold and Bitcoin respond to fear differently because they are built differently. Gold has centuries of dual-use demand, industrial and monetary, with no issuer and no counterparty risk. Bitcoin is a pure investment asset whose price moves on flows, sentiment, and access to leverage, which makes it react faster to both panic buying and panic selling.
- In some early 2026 news-driven shocks, Bitcoin briefly traded like a hedge before giving back gains as investors needed cash.
- Gold tended to hold or extend gains in the weeks that followed, particularly when the shock had a monetary or liquidity dimension.
- The BIS describes a "crypto multiplier" effect in which crypto assets fall further than traditional markets during stress because investors demand liquidity fastest from the most liquid, most recently purchased assets.
The deeper difference is policy sensitivity. Dollar strength and real interest rates weigh on gold because it carries no yield, but crypto carries that same opportunity cost plus a liquidity risk that gold does not share. Flight-to-quality favors gold. Flight-to-cash tends to hurt both assets, but it hurts crypto first and harder.
Why gold's safe-haven role is regime dependent
Gold's price behavior comes down to three channels working together or against each other.
- Opportunity cost: gold pays no yield, so rising real interest rates make holding it more expensive relative to bonds or cash.
- Convenience yield and safe-asset demand: during liquidity crunches or currency instability, investors pay a premium for gold's lack of counterparty risk.
- Dollar pricing: since gold trades in dollars globally, a stronger dollar mechanically pressures the price even when local demand is stable.
These channels align differently depending on the shock. A monetary policy surprise that cuts real yields and weakens the dollar tends to lift gold on two fronts at once. A geopolitical shock that spikes safe-asset demand without moving rates much can still lift gold, just less sharply. A commodity price shock, by contrast, often leaves gold flat or lagging because it does not touch the opportunity-cost or dollar channels directly.
Pro Tip: Watch real yields and the dollar index together. When both are falling, gold's conditions are aligned; when only one is moving, expect a weaker or shorter-lived reaction.

Over a multi-year horizon, these channels tend to average out in gold's favor when inflation or currency instability persists. Over weeks or months, they can pull in opposite directions and produce disappointing results even during a genuine crisis.
Implications for portfolio sizing and practical rules of thumb
Research on reserve portfolios gives a useful benchmark for individual investors too. The BIS finds that optimal gold allocations are typically small, in the 0 to 5% range, for portfolios with low duration risk. Allocations above 10% can be justified when duration risk or currency risk is large, and specific tail-risk hedging cases can support even higher weights.
BIS working-paper analysis shows gold allocations are generally small, typically under 5% in many standard criteria, rising higher only in cases where duration or extreme tail risk dominates the objective. That is a narrower range than the popular "5 to 10% of every portfolio" rule often repeated in personal finance content.
Practical tradeoffs follow from this:
- Gold can drag on returns during long equity rallies since it earns no yield and no growth premium.
- Physical gold, ETFs, and futures carry different liquidity, storage, and counterparty tradeoffs worth weighing before buying.
- Rebalancing on a schedule, rather than reacting to headlines, keeps the allocation aligned with its original purpose.
A workable approach: simulate a small allocation against your existing portfolio, set a rule for when you would increase it, such as a clear shift in real yields or reserve flows, and review the position on a fixed schedule tied to monetary policy meetings.
Publisher perspective: trading gold vs owning it
Strategic gold ownership and active gold trading serve different goals. Ownership is portfolio insurance, held through cycles. Active trading targets short-term price moves in XAUUSD and carries its own risk profile entirely separate from the hedging case above.
An auto-trading strategy focused exclusively on XAUUSD, executed automatically through the COPYX system, with independently verified results showing 18 consecutive winning months. Readers considering this route should verify claims directly rather than take them at face value.
- Check the live performance verification before funding any account.
- Understand the drawdown policy and how it is enforced.
- Review leverage rules since leverage changes the risk profile substantially.
- Confirm withdrawal terms before committing funds.
Pro Tip: Treat active gold trading and strategic gold ownership as separate line items with separate risk budgets, not one combined "gold allocation."
Author's quick take for investors today
Gold's case is conditional, not automatic. A modest default allocation, sized with the BIS reserve-portfolio evidence in mind, makes more sense than chasing headlines about record prices. Reserve flows, real yields, and dollar direction are the signals worth tracking before deciding to increase that allocation.
Document your rules before a crisis hits, not during one. Know your liquidity needs, know what instrument you actually hold, and treat any active trading exposure as a separate decision from long-term positioning. Combining a disciplined core allocation with cautious, verified active exposure is a more defensible stance than betting everything on one narrative about gold or Bitcoin.
— Paulo
An alternative for active gold exposure worth a closer look
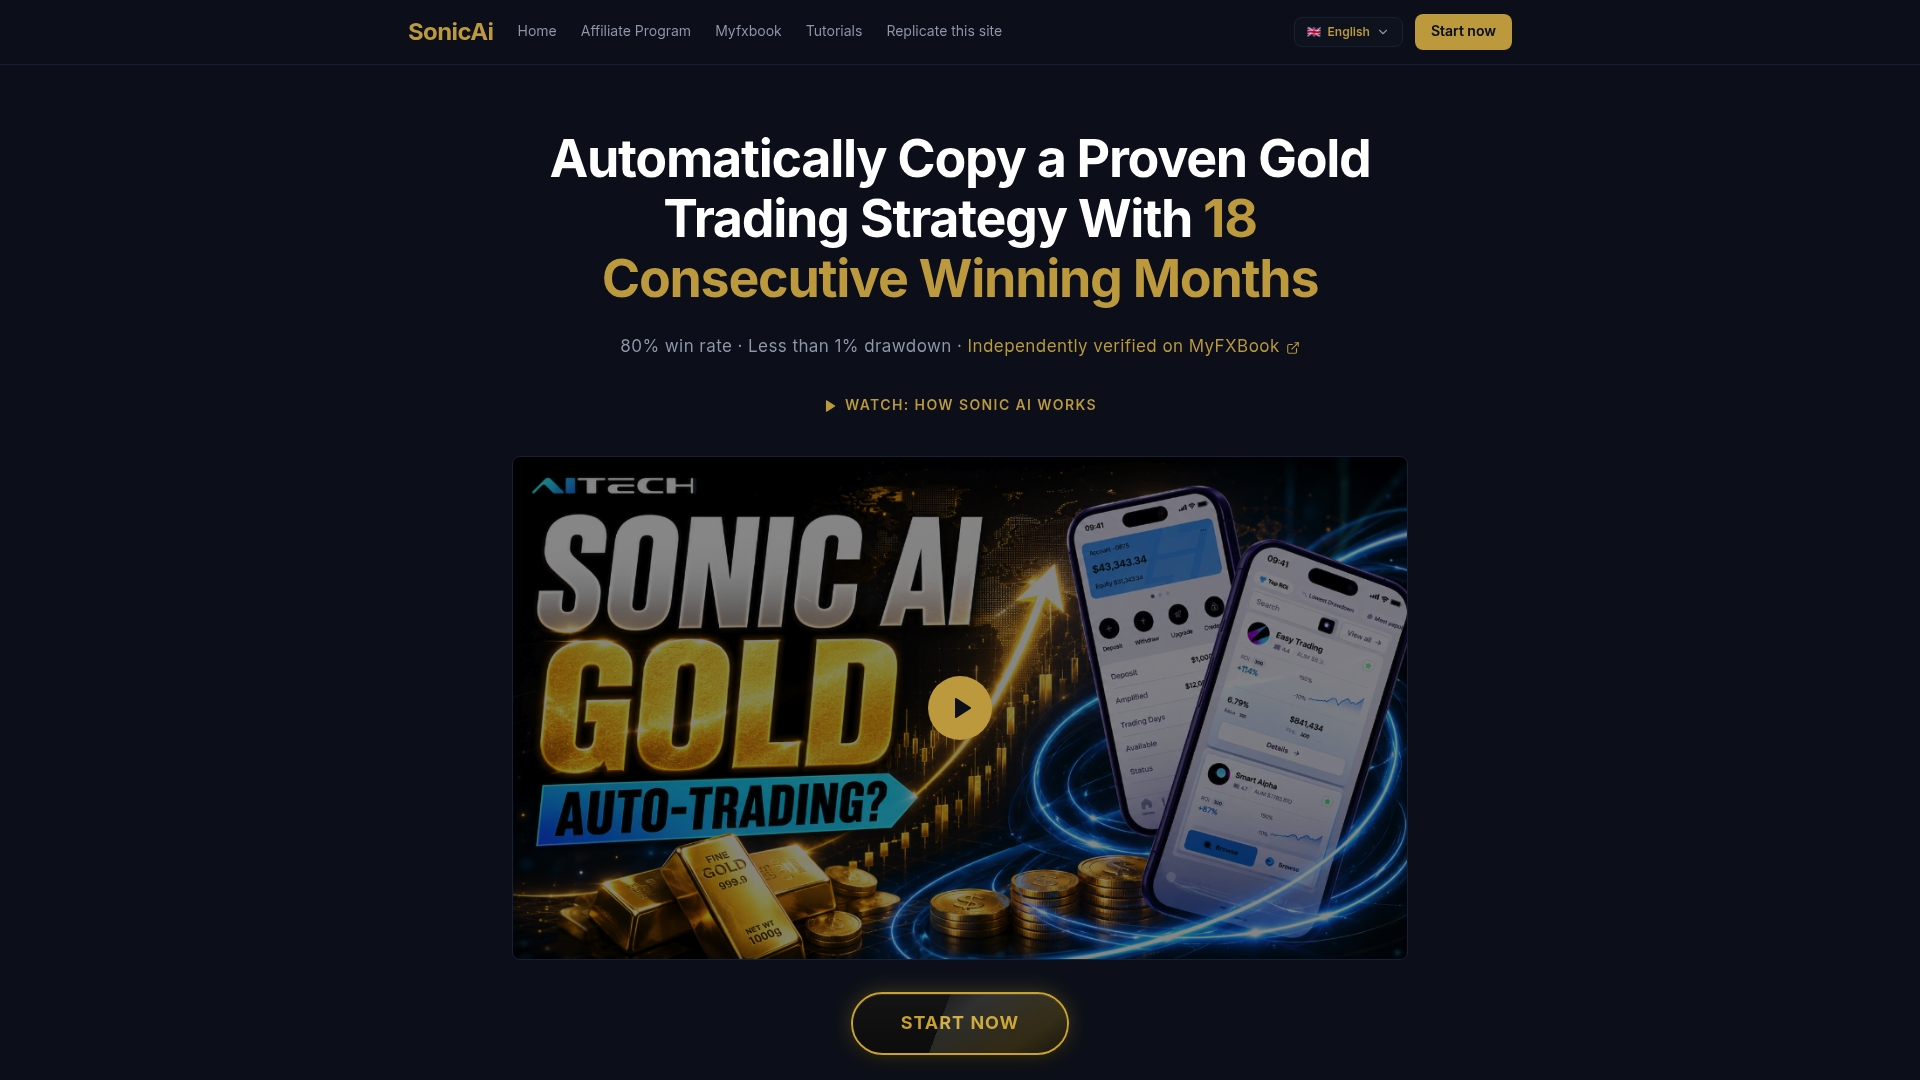
Readers who want exposure to gold's price moves, rather than long-term ownership, face a different problem: XAUUSD trading takes time, discipline, and constant attention to the same real-yield and dollar signals discussed above. Sonic AI is built around a professionally managed strategy focused exclusively on gold, executed automatically through COPYX so accounts copy trades without requiring hands-on decisions.
Before funding an account, review the fee structure and the platform's own performance data:
- Confirm the performance fee structure before depositing funds.
- Review verified results on the MyFXBook performance page.
- Compare standard, 12X, and 24X amplified accounts for different exposure levels.
Explore the Sonic AI platform directly to see current setup steps and account options.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Gold in central bank reserves: strategic considerations, market risks, and practical guidance (IMF Note No. 26/07)
- Stablecoins, money market funds and monetary policy (BIS working paper 1219)
- Is Gold Always a Safe-Haven Asset? (academic summary / Duke research page)
FAQ
Why does Dave Ramsey say not to buy gold?
Popular personal finance commentary often frames gold as unproductive because it pays no dividend, interest, or rental income compared to stocks or real estate. This view emphasizes long-term growth assets over non-yielding stores of value, a framing distinct from the reserve-manager research on gold's conditional hedging role.
What does Warren Buffett think of gold?
Buffett has long favored productive assets, businesses and property that generate cash flow, over gold, which he has described as an asset that just sits there without producing anything. That stance reflects a growth-investing philosophy rather than a judgment on gold's use as a portfolio hedge during specific market shocks.
Should I buy gold now or wait until 2026?
There is no single correct timing answer, since gold's near-term behavior depends on real interest rates, dollar strength, and the type of shock hitting markets. The BIS evidence suggests sizing a small allocation and adjusting it as those signals shift makes more sense than trying to time a single entry point.
Will gold hit $10,000 an ounce?
No dated, primary source in this article projects a specific price target that high, so any such figure should be treated as speculation rather than forecast. Gold's price path depends on the same real-yield, dollar, and reserve-flow dynamics discussed above, not a fixed timeline toward any round number.