What is sharpe ratio trading and why does it matter for gold?
The Sharpe ratio measures how much excess return a trading strategy generates per unit of risk. Specifically, it divides the portfolio's return above the risk-free rate by the standard deviation of those returns, then annualizes the result using the square root of trading periods (252 for daily data).
Raw returns tell only part of the story. A gold strategy posting 30% annually with violent swings is a different proposition than one posting 18% with steady, controlled drawdowns. The Sharpe ratio captures that difference in a single number.
Key benchmarks for evaluating trading strategies:
- Below 1.0: Acceptable, but not strong; volatility is high relative to excess return
- 1.0–2.0: Good; typical range for well-run systematic strategies
- Above 2.0: Very good; institutional-quality performance for algorithmic traders
- Above 3.0: Excellent on paper, but worth scrutinizing for overfitting
Sonic AI's gold strategy has delivered 18 consecutive winning months with independently verified results, an 80% win rate, and transparent performance reporting. COPYX automates trade copying from this verified strategy, so investors participate without manual execution.
Table of Contents
- How to interpret and apply the Sharpe ratio in automated gold trading
- A practical gold auto-strategy with a strong Sharpe ratio
- Sonicaigold puts a verified Sharpe ratio strategy within reach
- Key Takeaways
How to interpret and apply the Sharpe ratio in automated gold trading
Interpretation starts with context. A Sharpe of 1.5 on a gold strategy running daily bars is strong. The same figure on an intraday system needs adjustment: annualizing intraday data requires scaling by the correct number of trading intervals per year, not simply 252.
The ratio has a known limitation: it treats upside and downside volatility equally. A gold strategy with large positive spikes but small drawdowns gets penalized unfairly. The Sortino ratio corrects this by measuring only downside deviation, making it a useful companion metric. The Calmar ratio adds another dimension by comparing annualized return to maximum drawdown, which is particularly relevant for gold's periodic sharp corrections.
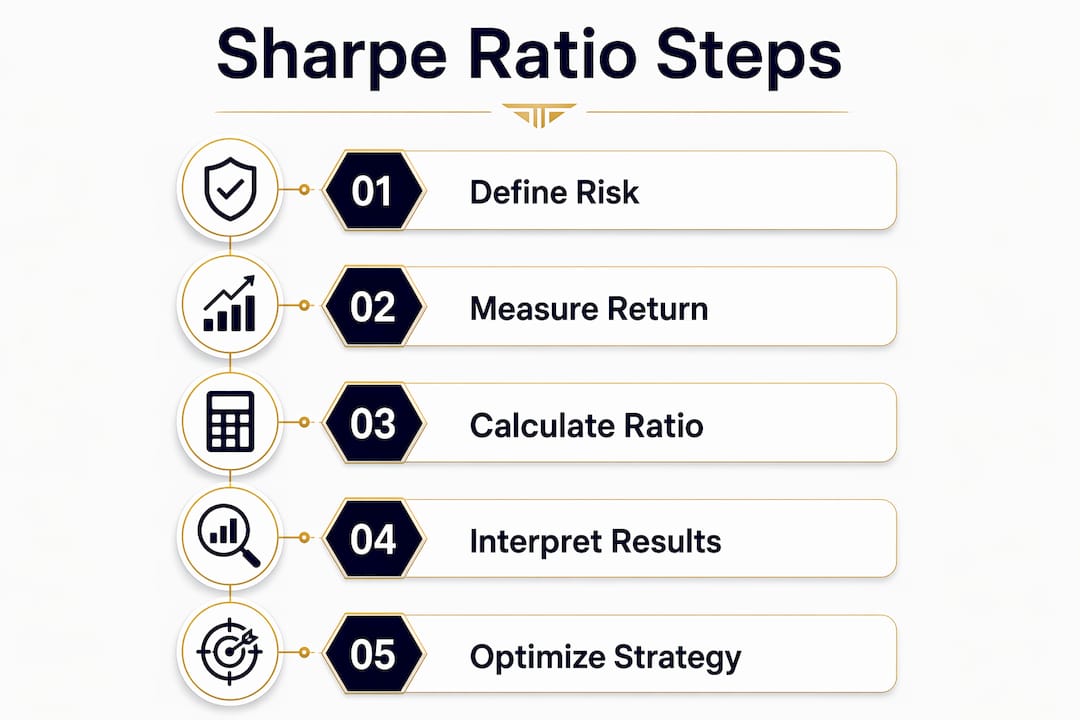
Over-optimizing for Sharpe during backtesting is a real risk. Strategies tuned to maximize this single metric often produce fragile systems that fail out of sample. Backtested Sharpe ratios above 3 are frequently a sign of curve fitting rather than genuine edge. Moderate ratios in the 0.8–1.2 range, sustained across different market regimes, often indicate more durable strategies.
Multi-objective optimization addresses this by balancing total return, risk, and volatility simultaneously. Strategies built this way tend to be more robust because no single metric dominates the design process.
Copy trading platforms use Sharpe ratio alongside win rate, drawdown, and verified track record to filter strategies worth replicating. COPYX applies this framework when connecting investors to Sonic AI's gold strategy.
Pro Tip: Use volatility-based position sizing rather than fixed dollar amounts. Scaling position size inversely to recent volatility keeps risk per trade consistent, which directly supports a higher and more stable Sharpe ratio in live trading.
A practical gold auto-strategy with a strong Sharpe ratio
Sonic AI's XAUUSD strategy illustrates what a well-constructed automated approach looks like in practice. The strategy focuses exclusively on gold, managed by an experienced team using a defined methodology. Performance is tracked and published through Myfxbook, providing third-party verification rather than self-reported figures.
Eighteen consecutive winning months with an 80% win rate and low drawdown produce the kind of consistent return profile that generates a strong risk-adjusted result. The consistency matters as much as the absolute return: steady monthly gains with controlled losses keep the standard deviation low, which is exactly what pushes the Sharpe ratio higher.
COPYX handles execution automatically. Investors connect their accounts and copy trades in real time, without needing to monitor charts or make individual trading decisions.
Sonicaigold puts a verified Sharpe ratio strategy within reach
Sonicaigold offers direct access to the Sonic AI gold strategy without the complexity of building or backtesting a system from scratch.
The strategy is independently verified, focused exclusively on XAUUSD, and has produced 18 months of consistent results with transparent reporting. COPYX handles trade execution automatically, so investors receive the risk-adjusted performance of a professionally managed strategy without manual involvement. For investors who want a verified, high-Sharpe gold trading approach running on their account, Sonicaigold is the direct path. Review the verified performance data and start copying the strategy today.
Key Takeaways
A Sharpe ratio signals institutional-quality risk-adjusted performance, and Sonic AI's gold strategy achieves strong, consistent results with multiple consecutive winning months verified independently.
| Point | Details |
|---|---|
| Sharpe ratio formula | Excess return divided by return standard deviation, annualized using the square root of trading periods. |
| Performance benchmarks | A ratio above 2.0 is very good for algorithmic traders; above 3.0 warrants scrutiny for overfitting. |
| Sortino and Calmar complement | Pair Sharpe with Sortino (downside-only) and Calmar (return vs. drawdown) for a complete risk picture. |
| Avoid single-metric optimization | Strategies tuned only for Sharpe often curve-fit; multi-objective optimization produces more robust results. |
| Sonicaigold verified track record | Sonic AI's XAUUSD strategy delivers 18 consecutive winning months with an 80% win rate, copied automatically via COPYX. |